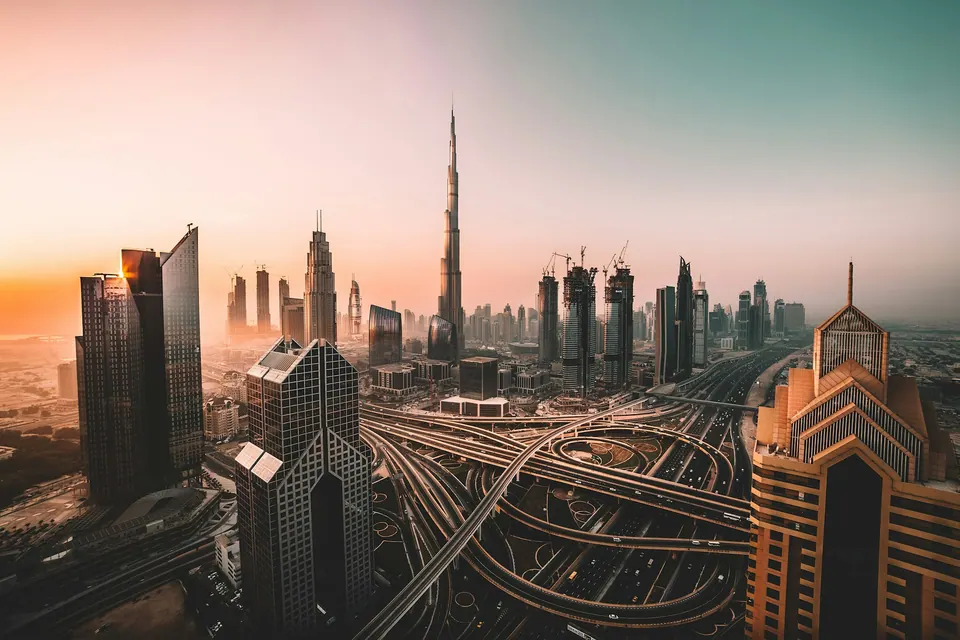
Dubai has done something no other prime market has managed at this scale: it has made the brand the building. On the latest reading of our Prime Index, operator-run branded residences in the emirate now sell at roughly a 35% premium over comparable non-branded stock — the widest spread of any market we follow, and still widening.
Why the premium is real
The premium is not paid for a logo. It is paid for a service contract, a design studio’s discipline, and a scarcity the best operators enforce by capping how many doors carry the name. When a hotel group licenses its brand to a residential tower, it typically controls the building’s design standards, the lobby aesthetic, and, crucially, the management of common areas, concierge, and building services for the long term. For a buyer — often one who will be in residence for fewer than ninety days a year — that guarantee of maintenance and presentation is worth a great deal.
There is also a liquidity argument. Branded product in Dubai resells faster and with a narrower bid-ask spread than comparable non-branded stock. International buyers, particularly those purchasing without an in-person inspection, are more willing to transact on a known operator’s product sight-unseen. That confidence premium is real, measurable, and compounds over time as the operator’s track record in the market deepens.
What the 35% figure does and does not mean
It would be a mistake to read the premium as uniform or permanent. At the top of the branded market — the most coveted operator names on the most prominent waterfronts — premiums are running meaningfully above 35%. At the lower end, where the brand is less global or the location less desirable, the differential is narrower and more contested. The 35% is an average across a diverse range of product.
Whether it holds depends on supply discipline. Dubai’s developer community is sophisticated about this; the better operators limit the number of branded developments they permit in any given cycle to protect scarcity. If that discipline weakens — if the market is flooded with branded product of varying quality over the next three years — compression is likely. Buyers who purchase today at a 35% premium and expect to sell at a 40% premium in five years are making a supply assumption as much as a market call.
For a fuller picture of the drivers and the current sales pipeline, the Dubai hub and our analysis of branded residences in Dubai set out the market in more detail. The short version: the premium is structurally justified, the demand for managed, lock-and-leave prime product is not going away, and Dubai has the infrastructure — legal, financial, and physical — to sustain it. What the market requires, and what the best operators appear to understand, is restraint in the count.